

Home & Hospital Visits Available | Call 24 hours a day
(1-866-426-3952)
FIGHTS!

What Happens If You Total a Leased Car
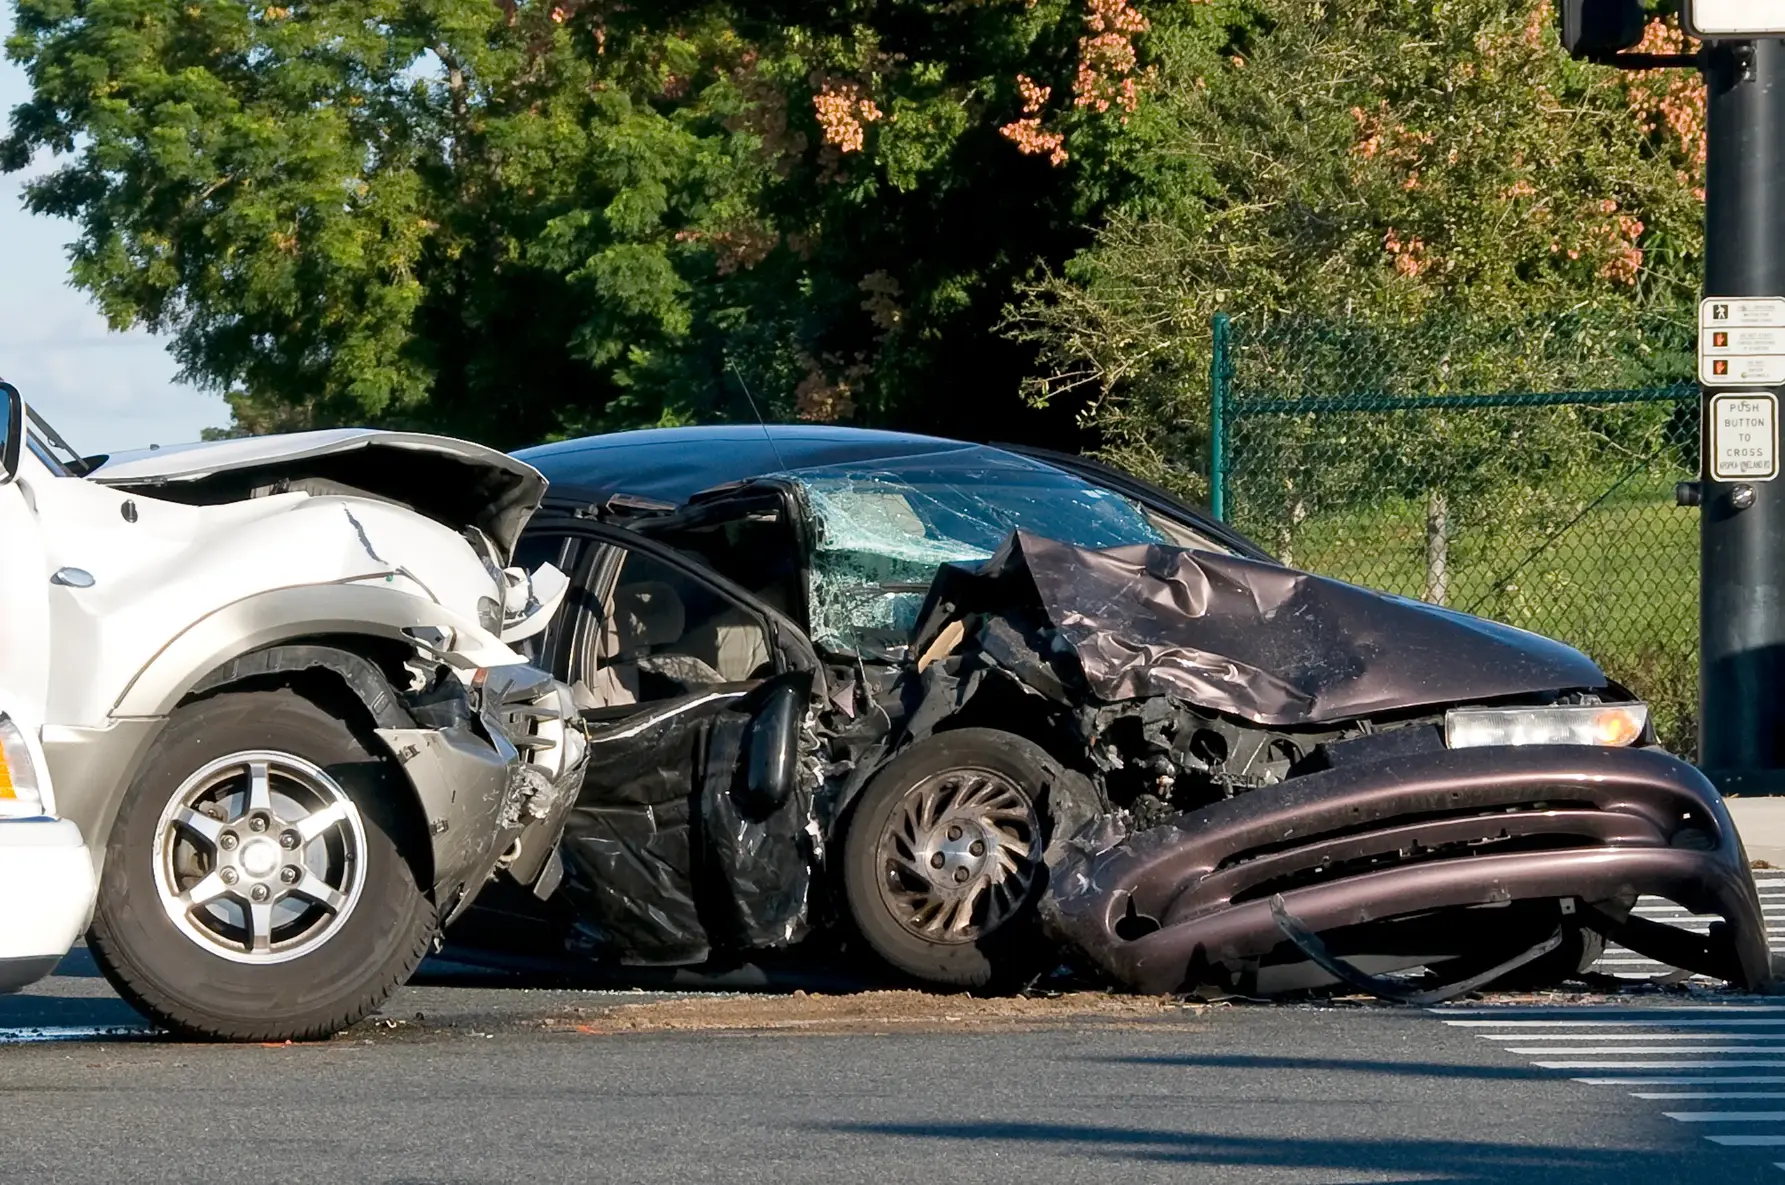
When you total a leased car in a car accident, the lease ends early, the insurance settlement goes toward what the leasing company is owed, and you may owe any shortfall unless gap coverage picks it up. Your lease and your insurance policy decide most of the details. Any personal injury claim from the crash is separate, and it belongs to you, not the leasing company.
When Is a Leased Car Considered Totaled in Texas?
Your insurer decides whether a car is a total loss under your policy. Texas law then labels the wreck for title purposes. Under Section 501.091 of the Texas Transportation Code, a car becomes a salvage motor vehicle when repair costs, excluding repainting and sales tax, exceed its actual cash value before the damage. The statute defines actual cash value as the car’s market value.
A car so badly wrecked or burned that it is only worth parts or scrap metal is a nonrepairable vehicle instead. On a lease, the title goes to the leasing company because it owns the car while you pay to use it.
Who Gets the Insurance Money When a Leased Car Is Totaled?
The settlement goes toward the leasing company’s payoff first. A totaled car ends the lease early, and according to the Federal Reserve’s consumer guide to vehicle leasing, you find what you owe by comparing the lease payoff with the settlement from your insurance company. If the settlement falls short, the difference is a deficiency you may have to pay. If it comes in higher, you have a surplus, and the lease explains how it is handled.
For example, if the lease payoff is $24,000 and the insurer values the car at $21,000, the $3,000 difference is the shortfall. Your lease’s total-loss and early termination provisions set how that number is calculated, and your policy shows who the insurer pays.
If another driver caused the crash, you can file the claim with that driver’s liability insurer, since Texas is not a no-fault state. Your own collision coverage, if you carry it, is another option while fault is sorted out.
Does Gap Coverage Pay What You Still Owe on a Lease?
Gap coverage is an agreement by the leasing company or a third party to pay the gap amount if the car is stolen or totaled. The Federal Reserve describes the gap amount as typically the amount by which the early termination payoff, not counting any past-due amounts, exceeds the car’s insured value. In the $24,000 payoff example, gap coverage would cover the $3,000.
Gap coverage usually doesn’t pay your insurance deductible, so you may still have to pay it. Many leasing companies offer gap coverage, but whether your lease has it depends on the paperwork you signed, so the lease file and any gap addendum show what applies to you.
How Long Does an Insurer Have to Pay a Total Loss Claim in Texas?
For a claim on your own policy, Texas law sets the timeline. Under Section 542.056 of the Texas Insurance Code, your insurer must tell you in writing whether it accepts or rejects the claim within 15 business days after it receives all the items, statements, and forms it requested, and it must explain any rejection. An insurer that needs more time has to explain why and then decide within 45 days of that notice.
Once the claim is accepted, Section 542.057 generally requires payment within five business days. An insurer that does not follow these deadlines can owe interest on the claim plus reasonable attorney’s fees under Section 542.060. These deadlines apply to claims against your own insurer, not against the other driver’s company.
How Long Do You Have to Sue Over the Crash That Totaled Your Leased Car?
Texas generally allows two years to file a lawsuit for damage to property or for personal injury under Section 16.003 of the Texas Civil Practice and Remedies Code. After a crash, that two-year clock usually starts on the day of the crash, when the right to sue first arises.
The vehicle and your injuries move on separate tracks under that same deadline. The car’s value goes toward the lease payoff, while compensation for your medical bills, lost wages, and pain belongs to you.
Steps That Help After a Leased Car Is Totaled
A few early actions and records make both the vehicle claim and the injury claim easier to resolve:
- Reporting the crash to your insurer promptly: The insurer’s 15-business-day clock does not start until it has everything it asked for.
- Notifying the leasing company in writing: Its reply shows the payoff amount and how it will apply the insurance settlement.
- Requesting the full lease file: The total-loss, early termination, and gap provisions decide what you may owe.
- Keeping dated copies of everything sent to the insurer: A record of when the claim file was complete shows when the deadlines began.
- Photographing the car and keeping repair estimates: These show the damage compared with what the car was worth.
Talking With a Texas Car Accident Lawyer at Gamez Law Firm After You Total a Leased Car
Losing your car and getting hurt in the same crash can leave you juggling a leasing company, an insurer, and medical appointments at once. In car accident claims, our team works with insurance adjusters to determine what your claim is worth, and we can help you find a rental car or a ride to and from work while the claim moves forward.
If you total a leased car in a crash someone else caused, Gamez Law Firm is ready to help. Call 210-736-4040 or contact us for a free consultation, and we can talk through both the car and your injuries.
Gamez Law Firm
Open 24 hours
