

Home & Hospital Visits Available | Call 24 hours a day
(1-866-426-3952)
FIGHTS!

How Is a Vehicle Considered Totaled?
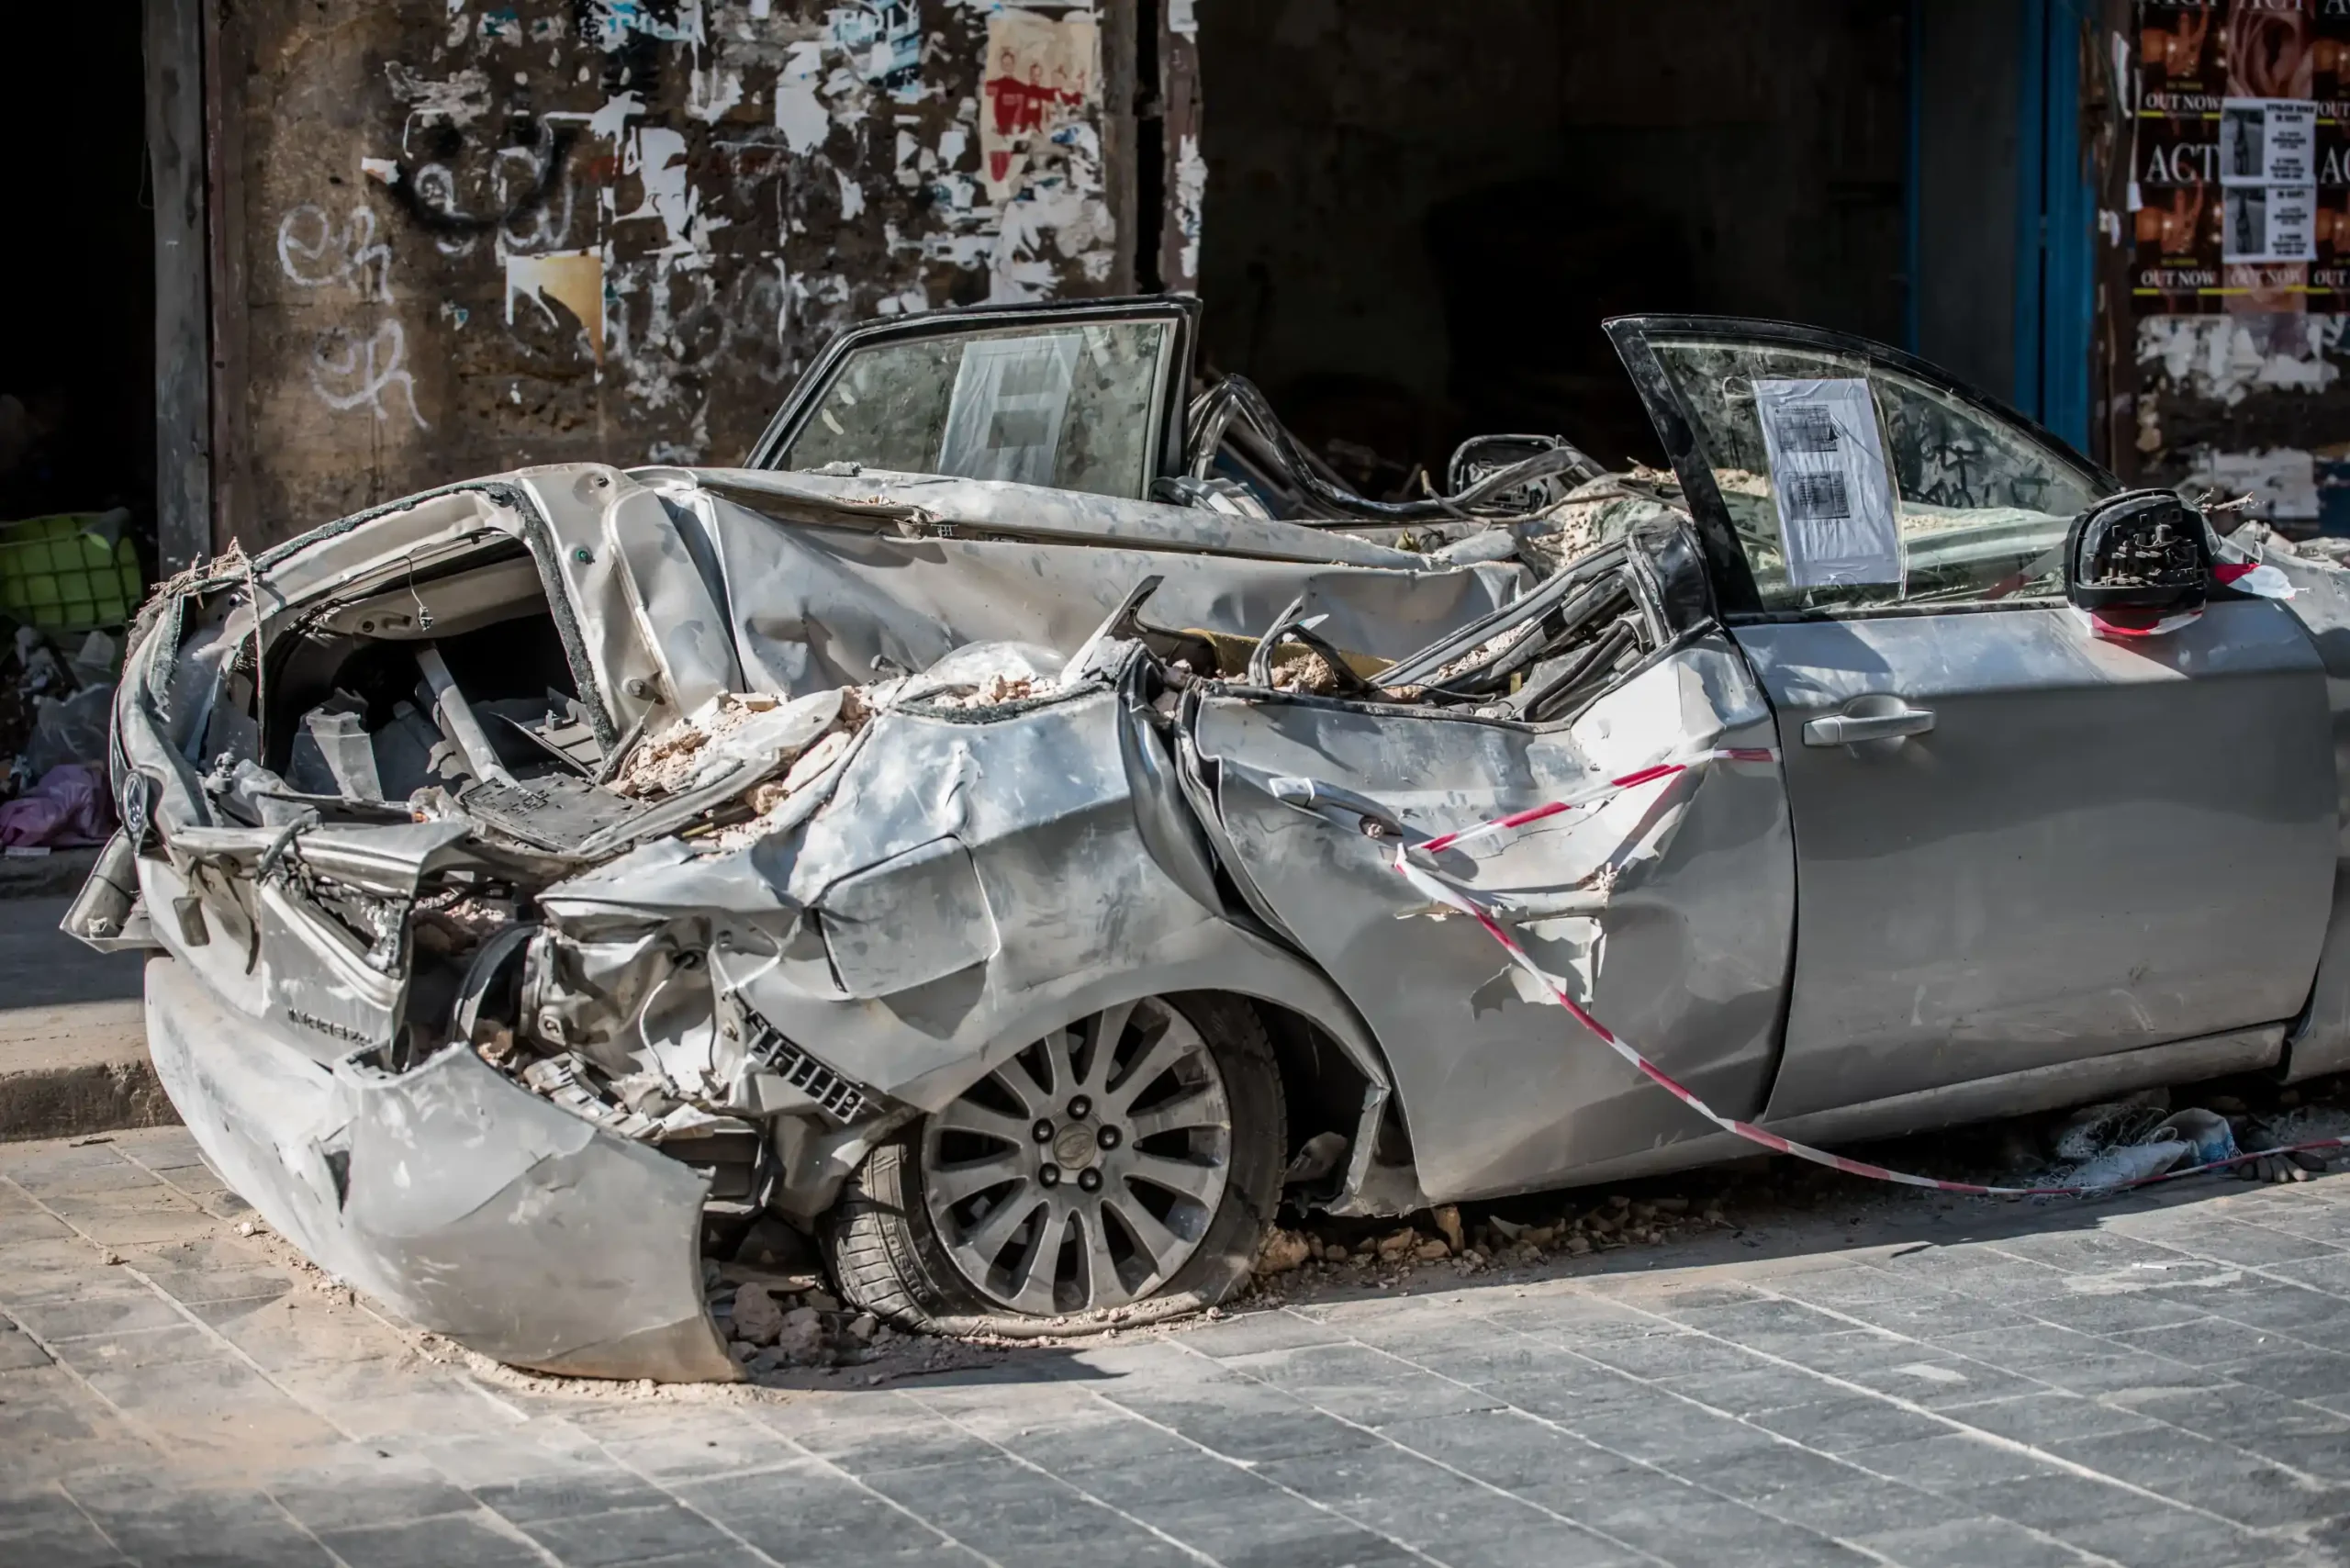
A vehicle is considered totaled when the insurance company decides that fixing it does not make financial sense compared with what the car was worth before the damage. Texas sets no single percentage that forces an insurer to make that call. The Texas Department of Insurance (TDI) explains that a company might total a car when the cost to repair it is close to its current value.
Texas law uses a separate test to decide whether a damaged car needs a salvage or nonrepairable title, and that title controls whether it can be driven again.
Totaled Car vs. Salvage Motor Vehicle Under Texas Law
Under Section 501.091 of the Texas Transportation Code, a car becomes a salvage motor vehicle when it has damage to, or is missing, a major component part and the cost of repairs exceeds its actual cash value immediately before the damage. Actual cash value is the car’s market value, meaning what a car like yours would have sold for right before the crash.
The repair figure leaves out the materials and labor for repainting, along with sales tax on the total repair bill. The statute lists 13 major component parts, which fall into these groups:
- The engine, transmission, or frame
- A fender, the hood, a bumper, or a quarter panel
- A door into the passenger compartment
- A deck lid, tailgate, or hatchback
- The cab of a truck or the cargo box of a pickup or other light truck
- The body, roof, or floor pan of a passenger vehicle
The same section counts sudden damage from a wreck, fire, flood, or stripping. Hail damage and damage only to exterior paint do not count. Because the insurer’s decision and the salvage test are separate, a car can be totaled by an insurer without becoming a salvage vehicle, for example when repairs come close to its value without exceeding it.
What Does the Insurance Company Pay for a Totaled Car?
For a totaled car, the insurer pays its actual cash value, which TDI puts in insurance terms as the cost to replace the car minus depreciation. A 10-year-old car is paid as a 10-year-old used car.
That payment can fall short of what is still owed on a car loan. Guaranteed auto protection, or gap insurance, sold by dealers and lenders, is meant to cover that shortfall. A rental car can also end sooner than expected: TDI notes that once your own insurer totals the car, it might stop paying for the rental a few days after telling you. If another driver caused the crash, that driver’s insurer pays for the rental.
Can You Keep a Totaled Car or Drive It Again?
You can ask to keep a totaled car. If you do, the insurer subtracts the car’s salvage value from the settlement. For example, if a car was worth $12,000 before the crash and the insurer puts its salvage value at $1,500, keeping it cuts the payment to $10,500, before any deductible. If the car meets the salvage or nonrepairable definition, Texas law then requires the insurer to report the payment to the Texas Department of Motor Vehicles, and the car cannot be sold until it carries a salvage or nonrepairable title.
Which of those two titles the car gets decides its future. Section 501.09111 of the Texas Transportation Code sets out what each owner may do:
| What the owner may do | Salvage title | Nonrepairable title |
| Possess, transport, dismantle, or scrap it | Yes | Yes |
| Sell or transfer the car or its parts | Yes | Yes |
| Repair, rebuild, or reconstruct it | Yes | No |
| Register it or drive it on a public highway | No | No |
A salvage car can return to the road once it is repaired and the owner applies for a new title, which shows its former condition to every future owner. A nonrepairable car, one damaged so badly that it is worth only parts or scrap metal, can never be retitled or registered.
How Long Does an Insurer Have to Pay After a Car Is Totaled?
Texas prompt-payment rules apply when the claim is made under your own policy, which the law calls a first-party claim. They do not cover a claim against the at-fault driver’s insurer. The timeline under your own policy:
- Decision: The insurer must accept or reject the claim in writing within 15 business days after it receives all the items, statements, and forms it requires, under Section 542.056 of the Texas Insurance Code. If it needs more time, it must say why within that window and then decide within 45 more days.
- Payment: Once the insurer says it will pay, the money is due within five business days.
- Late payment: For a collision claim, a liable insurer that misses these deadlines owes 18% yearly interest on the claim as damages, plus reasonable attorney’s fees.
Because the clock starts only when the insurer has everything it asked for, a record of the date each document was sent makes it easier to tell when a deadline has passed.
What If You Disagree With the Insurer’s Total Loss Decision?
TDI notes that a company might raise its offer if you can show your car would sell for more. Written price quotes from used car dealers for a similar car are the kind of proof it points to. When the insurer still will not pay more, TDI describes the appraisal process. Each side hires an appraiser, the two choose an umpire, and the umpire’s decision binds both sides. You pay for your appraiser and half of the umpire’s costs, and appraisal applies only to disputes with your own insurer.
A claim against the at-fault driver works differently. Under Section 16.003 of the Texas Civil Practice and Remedies Code, a property damage lawsuit generally has a two-year deadline that starts when the claim accrues, or legally arises. When the crash also caused injuries, the vehicle is only one part of a car accident claim, and the same deadline applies to the injury side.
Get Help With Your Totaled Car From Gamez Law Firm
Losing a car in a crash can leave you without a way to work while the insurer runs its numbers. Our team at Gamez Law Firm helps clients find a doctor and secure a rental car at no cost to them. If your car was totaled in a crash someone else caused, contact us or call 210-736-4040 to schedule a free consultation about your options.
Open 24 hours
