

Home & Hospital Visits Available | Call 24 hours a day
(1-866-426-3952)
FIGHTS!

Bodily Injury Liability Insurance in Texas: What It Actually Pays
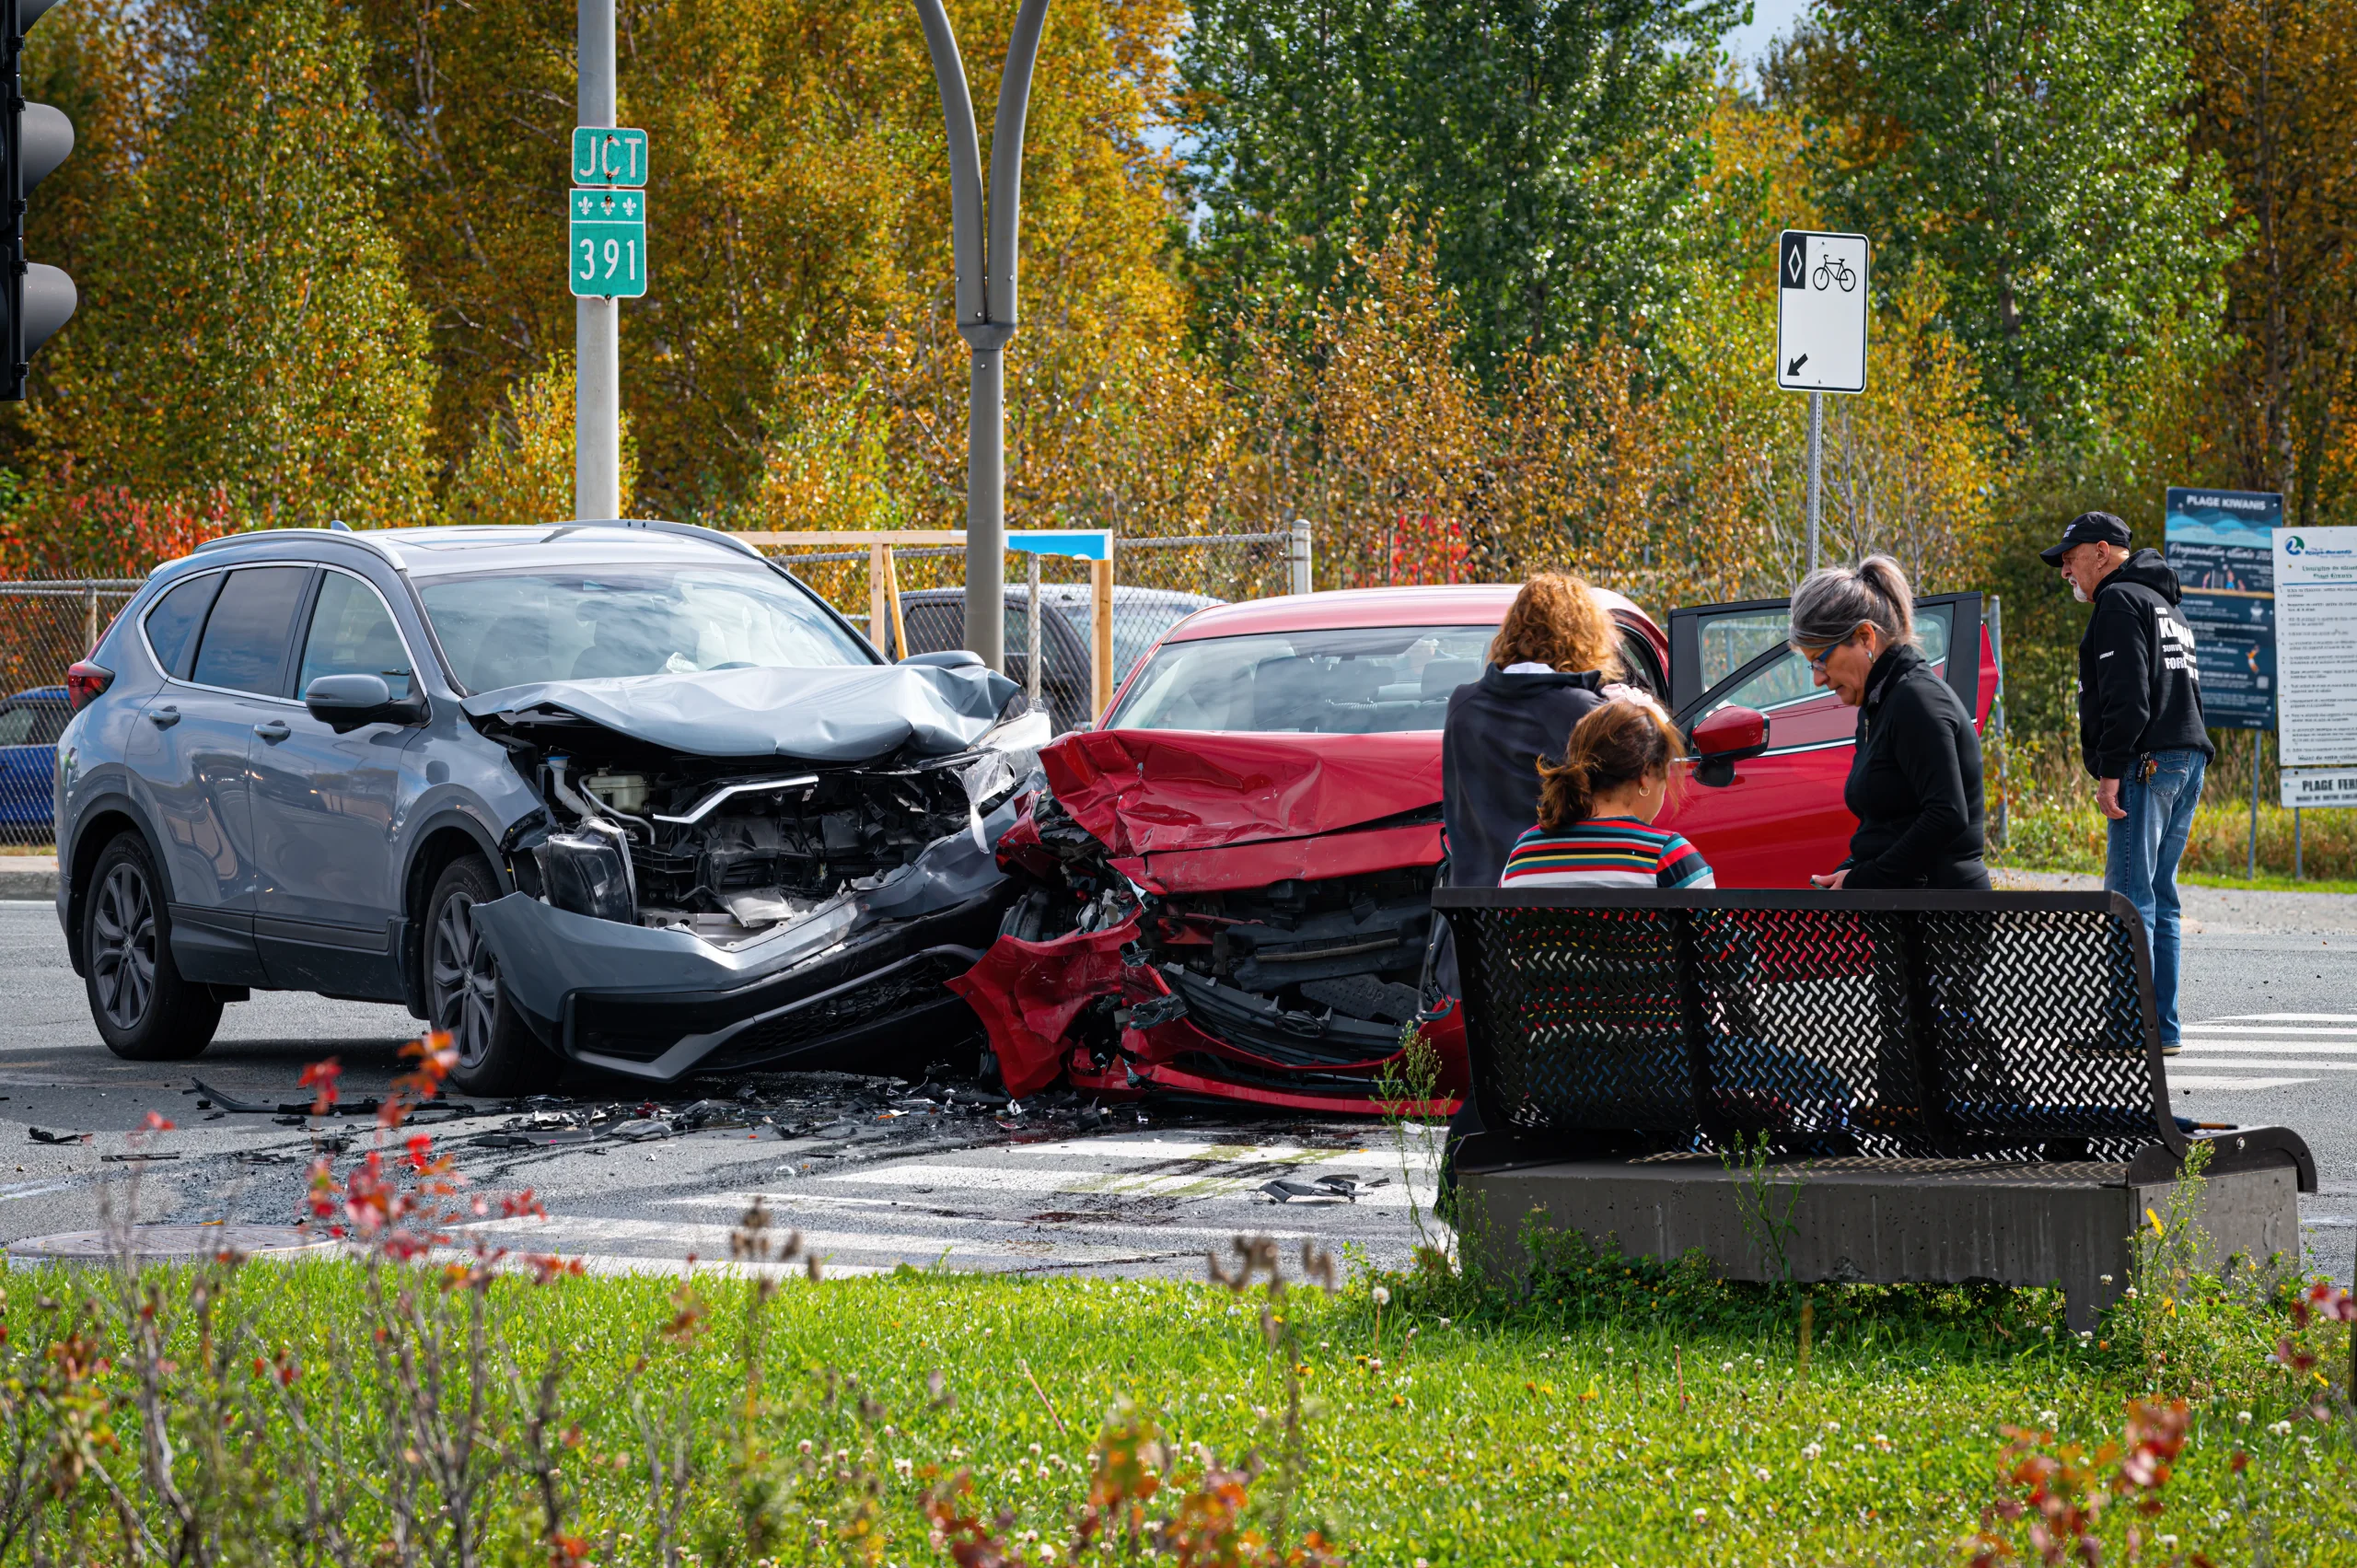
Bodily injury liability insurance in Texas pays for financial losses and intangible harm due to injuries you cause other people in a crash, not your own medical care or vehicle repairs. Every driver in Texas has to carry bodily injury insurance, though the required amount is well below what a serious collision costs.
What Is Bodily Injury Liability?
What is bodily injury liability doing on a policy you bought for yourself? It pays the medical expenses and related costs of anyone you hurt or kill in a car accident, which is the trade the state requires in exchange for a license plate. Your own broken arm and your own bumper fall under different coverages entirely.
What Losses Does Bodily Injury Insurance Cover?
Bodily injury insurance follows the injured person, not the vehicle. Anyone the at-fault driver hurts draws from that policy, including passengers and pedestrians. It consists of economic damages and non-economic damages:
- Medical treatment: These are the costs of fixing the harm, starting with the ambulance and running through hospital stays, surgery, imaging, and months of physical therapy.
- Lost income: Money the injured person did not earn while healing, along with reduced earning power when the body no longer handles the same job.
- Pain and mental anguish: Injury claims include payment for what the person went through, which insurers value separately from any bill.
- Death claims: When a crash kills someone, the policy covers burial costs and the losses that the surviving family members carry.
Economic damages come with paperwork, like billing statements and pay stubs. The non-economic damages, by contrast, get argued over a phone line until somebody names a number.
Texas Minimum Coverage Limits and How They Work
Texas sets a floor and lets drivers buy more coverage above it. Under Texas Transportation Code § 601.072, a policy has to carry at least three amounts, printed on your declarations page as 30/60/25:
- $30,000 for the injuries of one person in one crash
- $60,000 for everyone injured in that same accident
- $25,000 for property damaged in that wreck
Insurance agents market the coverage as bodily injury and property damage liability, combining two forms of protection under one premium. The first two policy numbers apply to bodily injury claims.
The middle figure is the total available per accident. So, four injured passengers share $60,000, with no one receiving more than $30,000.
How Much Coverage Texas Drivers Actually Need
Minimum limits vanish quickly. One night in a trauma unit and a single orthopedic surgery can pass $30,000 before anyone calculates the value of non-economic damages, and the driver who caused it stays personally on the hook for the rest.
Shopping for bodily injury and property damage limits comes down to what you own and what you drive past every day. The Texas Department of Insurance suggests drivers consider buying more than the minimum, since a multi-vehicle wreck or a totaled newer truck can blow through 30/60/25 quickly.
Higher limits provide more money for the injured person while shielding your personal assets from an unpaid judgment. The contrast is clear in commercial vehicle accidents, where liability coverage limits are typically far higher than those on a personal auto policy.
What Happens When the At-Fault Driver’s Limits Run Out?
The answer is usually in your own policy. Under Texas Insurance Code § 1952.101, an insurer cannot issue an auto policy in this state without providing uninsured and underinsured motorist coverage unless the named insured rejects it in writing, so many drivers carry it without realizing it.
Underinsured motorist coverage picks up the gap when the other driver’s limit stops short of your losses. Suing the driver personally is another route, but a judgment collects nothing from someone without assets, which is why the search for a second policy comes first.
Other coverage layers hide in ordinary places, and finding one changes what a claim is worth. A few are worth checking after any collision, such as:
- An employer’s policy when the driver was on the clock
- A rental company’s coverage on a borrowed vehicle
- A household policy covering a relative in someone else’s car
- A rideshare policy when meeting set app standards
- An umbrella policy above the auto coverage
None of that appears on a crash report. An attorney has to request declaration pages and ask whether the driver was making a delivery, driving a company truck, or running an errand for a boss.
Bodily Injury Liability Limits Should Not Decide What You Recover
An adjuster who says the policy “only has $30,000 on it” is quoting a limit, not the value of your injuries. Finding a second policy, an employer behind the driver, or coverage you already pay for takes digging, and at Gamez Law Firm, the first conversation is free.
Four decades of injury work in San Antonio back that call, and we take our fee from a recovery instead of your bank account. Call 210-736-4040 at any hour, and ask for a home or hospital visit if getting to an office is out of the question.
Every client gets a cell phone number for our lawyers at Gamez Law Firm, so Sunday questions don’t wait until Monday. Spanish speakers can have their entire case handled in Spanish, and you can contact our firm online to learn how much bodily injury liability coverage is really in play.
Contact a San Antonio Car Accident Lawyer at Gamez Law Firm
We serve all areas in San Antonio and throughout Texas.
Gamez Law Firm
2943 Mossrock, San Antonio, TX 78230
Open 24 hours
Find us with our GeoCoordinates: 29.51192751788769, -98.53749172596612
